
The UK construction industry operates differently from many other sectors when it comes to tax. It relies heavily on self-employed workers, subcontractors and businesses working across multiple short-term projects, which can make tax reporting more complicated.
The Construction Industry Scheme, commonly known as CIS, was introduced to manage how tax is deducted from payments made for construction work.
If you are a contractor, subcontractor, sole trader or limited company working within construction, understanding CIS is essential. It affects how subcontractors are verified, how payments are calculated, how much money is deducted and how those deductions are reported to HMRC.
This guide explains what CIS is, who must register, which work is covered and how contractors and subcontractors should manage their responsibilities.
What Is the Construction Industry Scheme?
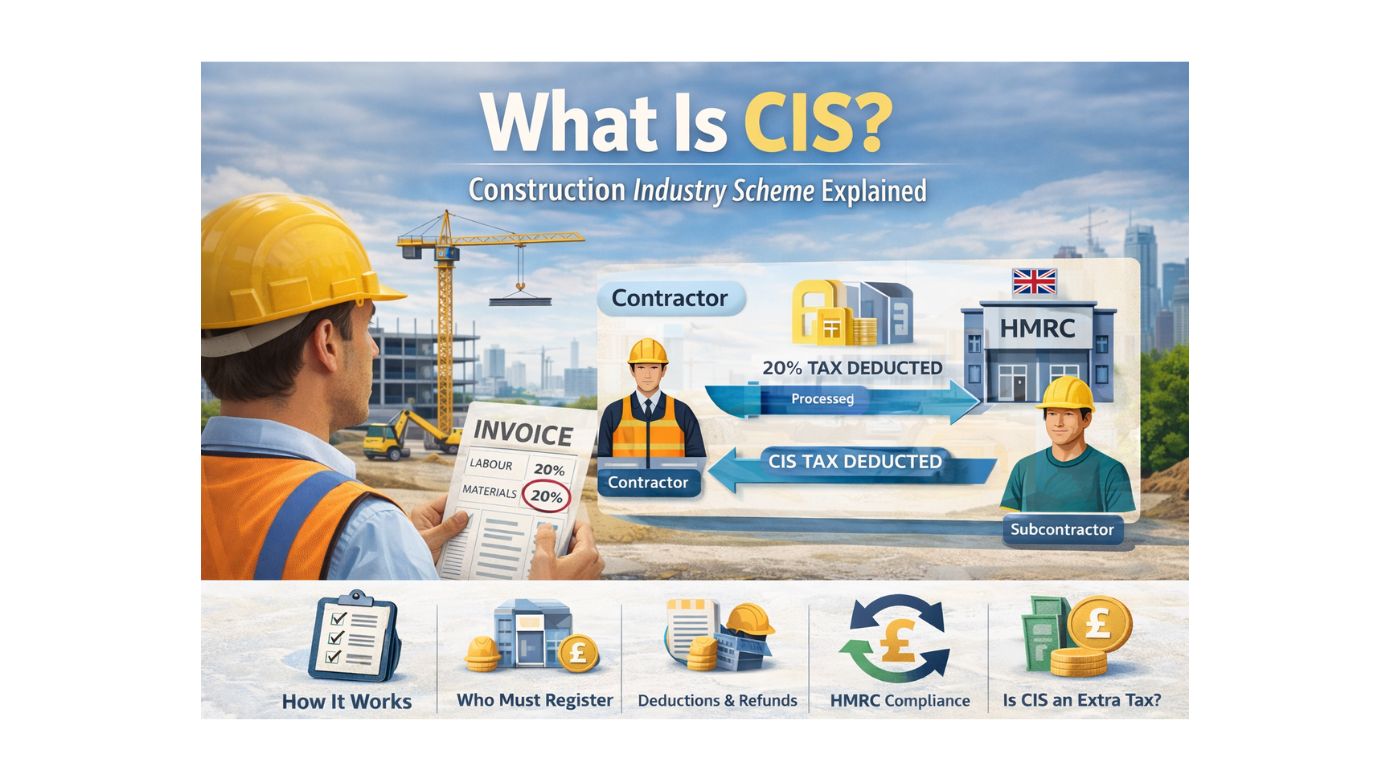
The Construction Industry Scheme is a tax deduction system for payments made within the UK construction industry.
Under CIS, contractors may need to deduct money from payments made to subcontractors and pass those deductions to HMRC. The subcontractor receives the remaining net payment.
The amount deducted is treated as an advance payment towards the subcontractor’s tax liabilities. It is not an additional tax charged on top of the tax the subcontractor already owes.
At the end of the relevant accounting period:
- Sole traders and partners report their full income and CIS deductions through Self Assessment.
- Limited companies normally offset CIS deductions suffered through their payroll reporting.
- Any remaining tax liability must still be paid.
- A repayment may be due where deductions exceed the final liability.
Why Does CIS Exist?
The construction industry regularly uses subcontracted labour, temporary engagements and project-based working arrangements. This flexibility is commercially useful, but it can make tax collection and reporting harder to monitor.
CIS creates a structured process under which contractors:
- Check the tax status of subcontractors.
- Apply the deduction rate given by HMRC.
- Report subcontractor payments every month.
- Pay deductions to HMRC.
- Give subcontractors evidence of the deductions made.
For subcontractors, CIS spreads tax deductions across the year rather than leaving the entire liability to be settled after the tax year ends.
However, CIS does not guarantee that the correct final amount of tax has been paid. Subcontractors must still complete the appropriate tax reporting and settle any remaining balance.
Who Does CIS Apply To?
CIS affects contractors who pay for construction work and subcontractors who are paid to carry it out.
Contractors
You normally count as a CIS contractor if you pay subcontractors to carry out construction work.
This includes traditional construction businesses such as builders, property developers and civil engineering companies.
A business whose main activity is not construction can also become a deemed contractor if it spends more than £3 million on construction work during the 12 months following its first relevant payment.
Contractors must register for CIS before operating the scheme.
Subcontractors
A subcontractor is an individual or business that carries out construction work for a contractor.
A subcontractor can operate as:
- A sole trader.
- A partnership.
- A limited company.
- A trust or another qualifying business structure.
Subcontractors are not legally required to register for CIS, but an unregistered or unverifiable subcontractor will normally have deductions made at the higher rate of 30%.
A business can be both a contractor and a subcontractor. For example, a building company may be paid as a subcontractor on one development while employing its own subcontractors on another project.
CIS Does Not Apply to Employees
CIS applies to self-employed subcontractors, not employees who should be paid through PAYE.
Registering a worker under CIS does not automatically make that person self-employed. The contractor must consider the reality of the engagement, including how the work is controlled, whether substitution is allowed, who carries financial risk and how the working relationship operates.
When submitting a monthly CIS return, the contractor must declare that the employment status of the subcontractors has been considered.
Incorrectly treating an employee as a subcontractor can lead to unpaid PAYE, National Insurance contributions, interest and penalties.
What Construction Work Is Covered by CIS?
CIS covers most construction work carried out on permanent or temporary buildings, structures and civil engineering projects in the UK.
Work commonly covered by CIS includes:
- Site preparation and groundworks.
- Building and structural work.
- Alterations and extensions.
- Repairs and renovations.
- Demolition and dismantling.
- Bricklaying and plastering.
- Carpentry and joinery.
- Roofing.
- Painting and decorating.
- Installing heating, lighting, power, water and ventilation systems.
- Internal cleaning carried out as part of an ongoing construction project.
- Scaffolding and other work integral to the construction operation.
Work That May Be Excluded
Some activities connected with the construction industry are excluded when supplied independently. These can include:
- Architectural and surveying services carried out in a normal professional capacity.
- Consultancy work involving designs, plans or technical reports without responsibility for supervising construction labour.
- The manufacture and delivery of construction materials where no installation or construction work is included.
- The delivery of materials without labour.
- Carpet fitting supplied as a standalone service.
- Site services such as catering, medical services or security where they do not form part of construction operations.
Mixed contracts need particular care. If a contract includes both construction and non-construction work, the entire payment may fall within CIS.
What Must a CIS Contractor Do?
Operating CIS involves more than simply deducting 20% from an invoice. Contractors must follow a sequence of checks, calculations and reporting obligations.
- Register as a contractor. The business must register with HMRC before it begins operating CIS.
- Check employment status. The contractor must establish that the worker is genuinely self-employed for the engagement.
- Verify the subcontractor. HMRC will confirm whether deductions should be made at 20%, 30% or 0%.
- Calculate the deduction correctly. VAT and qualifying material costs must be excluded before the deduction percentage is applied.
- Pay the subcontractor. The contractor pays the net amount after any required deduction.
- Provide a payment and deduction statement. Where a deduction is made, the statement must normally be provided within 14 days after the end of the relevant tax month.
- Submit a monthly CIS return. The return reports payments and deductions for the relevant tax month.
- Pay deductions to HMRC. The deductions are paid alongside PAYE and National Insurance liabilities.
- Maintain complete records. Invoices, calculations, statements and verification details must be retained.
How to Verify a Subcontractor
Before making the first payment to a subcontractor, a contractor may need to verify them through HMRC’s CIS service or recognised commercial software.
The contractor will usually need details such as the subcontractor’s:
- Legal or trading name.
- Unique Taxpayer Reference.
- National Insurance number for a sole trader.
- Company registration number for a limited company.
- Partnership details where applicable.
HMRC will provide the deduction status and, where appropriate, a verification reference number.
A subcontractor used previously may need to be verified again if they have not appeared on a CIS return during the current or previous two tax years.
CIS Deduction Rates
| Subcontractor Status | Deduction Rate | What It Means |
|---|---|---|
| Registered subcontractor | 20% | The standard rate is deducted from the qualifying part of the payment. |
| Unregistered or unverifiable subcontractor | 30% | The higher rate applies where HMRC cannot confirm standard or gross payment status. |
| Gross payment status | 0% | The subcontractor is paid without CIS deductions and remains responsible for paying its tax liabilities. |
The contractor should always use the rate provided by HMRC during verification rather than assuming which rate applies.
How Are CIS Deductions Calculated?
CIS deductions are not necessarily applied to the full value of the subcontractor’s invoice.
The contractor begins with the gross invoice amount and removes amounts relating to:
- VAT.
- Materials purchased directly by the subcontractor.
- Consumable stores that become unusable through the work.
- Fuel used for the work, excluding ordinary travelling costs.
- Plant hire for the job.
- The cost of manufacturing or prefabricating materials.
The relevant CIS percentage is then applied to the amount remaining.
Example of a CIS Deduction
A registered subcontractor submits the following invoice:
- Labour: £4,000
- Qualifying materials purchased by the subcontractor: £1,000
- Subtotal before VAT: £5,000
- VAT: £1,000
- Total invoice: £6,000
The deduction is calculated on the £4,000 labour element:
£4,000 × 20% = £800 CIS deduction.
The subcontractor would receive £5,200, consisting of the £4,000 labour charge, £1,000 materials and £1,000 VAT, less the £800 deduction.
The contractor should retain evidence supporting the material costs. Estimating or excluding unsupported material amounts can lead to an incorrect deduction.
Gross Payment Status
Gross payment status allows an eligible subcontractor to receive payments without CIS deductions.
This can improve cash flow, but it does not remove the subcontractor’s tax obligations. The business must still report its income and pay Income Tax, National Insurance or Corporation Tax as applicable.
To qualify, the business must satisfy HMRC that:
- It carries out construction work or provides labour for construction work in the UK.
- It operates through a bank account.
- It has maintained an acceptable record of tax compliance.
- It meets the applicable turnover test.
The minimum qualifying turnover, excluding VAT and materials, is generally:
- £30,000 for a sole trader.
- £30,000 for each partner or at least £100,000 for the partnership.
- £30,000 for each director or at least £100,000 for the company.
HMRC reviews gross payment status regularly. Late returns, unpaid tax or other compliance failures can place the status at risk.
Monthly CIS Returns and Deadlines
The CIS tax month runs from the sixth day of one month to the fifth day of the following month.
Contractors must submit their monthly return by the 19th following the end of the tax month.
For example, a return covering payments made between 6 May and 5 June must reach HMRC by 19 June.
The return must include:
- The subcontractors paid during the period.
- The gross amounts paid before VAT.
- Relevant material costs.
- The deductions made.
- Confirmation that employment status was considered.
- Confirmation that subcontractors requiring verification were verified.
CIS deductions must normally be paid to HMRC by the 22nd of the month where payment is made electronically, or by the 19th where payment is sent by post.
Nil Returns From April 2026
From 6 April 2026, a mainstream contractor that has not paid any subcontractors during a CIS tax month must either:
- Submit a nil return by the 19th; or
- Tell HMRC in advance that the scheme will be inactive.
A contractor expecting to make no subcontractor payments for several months can request that the scheme be made inactive for up to six months.
Payment and Deduction Statements
Where a CIS deduction is made, the contractor must provide the subcontractor with a payment and deduction statement.
The statement should show:
- The contractor’s details.
- The subcontractor’s details.
- The gross payment.
- The cost of materials.
- The CIS deduction.
- The relevant tax month.
The statement must normally be provided within 14 days after the end of the tax month. For example, a statement covering 6 May to 5 June should be supplied by 19 June.
Subcontractors should retain every statement because it provides evidence of the tax deducted from their income.
CIS and VAT
CIS and VAT are separate systems, but both can apply to the same construction transaction.
VAT is excluded before the CIS deduction is calculated. The subcontractor’s gross payment reported on the CIS return is also recorded before VAT.
Some construction transactions are additionally affected by the VAT domestic reverse charge. Where the reverse charge applies, the customer accounts for the VAT rather than paying it to the supplier.
The VAT reverse charge has separate conditions and should not be assumed to apply merely because a transaction falls within CIS.
Accurate VAT records and returns are particularly important where a business operates both CIS and the domestic reverse charge.
CIS for Sole Traders and Partnerships
A sole trader or partner who has CIS deductions taken must still report the full value of their income through Self Assessment.
The tax return should include:
- The full gross income shown on invoices.
- Allowable business expenses.
- The CIS deductions shown on payment and deduction statements.
HMRC calculates the final Income Tax and National Insurance liability and deducts the CIS tax already withheld.
If the CIS deductions exceed the amount owed, a repayment may be due. If the deductions are insufficient, the remaining balance must be paid.
CIS deductions do not remove the obligation to submit a tax return.
CIS for Limited Companies
Limited companies must handle deductions suffered differently from sole traders.
A company paid under deduction should not normally claim the deductions directly through its Corporation Tax return.
Instead, the company reports the year-to-date CIS deductions through an Employer Payment Summary as part of its payroll reporting.
HMRC offsets the CIS deductions against amounts the company owes for:
- PAYE Income Tax.
- Employer and employee National Insurance contributions.
- Student Loan deductions.
- CIS deductions the company has made from its own subcontractors.
Where the amount suffered exceeds the company’s liabilities for a month or quarter, the balance is carried forward within the same tax year.
After the end of the tax year, any excess that cannot be offset may be refunded or applied against Corporation Tax once the final payroll submissions have been received.
Accurate payroll and CIS records are essential because HMRC may request evidence supporting the amount claimed.
How Long Must CIS Records Be Kept?
Contractors must keep their CIS records for at least three years after the end of the tax year to which they relate.
Records should include:
- Subcontractor invoices.
- Verification details and reference numbers.
- Evidence of material costs.
- Payment records.
- CIS deduction calculations.
- Monthly return information.
- Payment and deduction statements.
- Records of deductions offset through payroll.
Records must be made available if requested by HMRC. Missing records can lead to penalties and make it difficult for subcontractors to prove deductions or claim repayments.
CIS Penalties for Late Returns
Monthly CIS returns must be filed by the 19th. Automatic penalties can apply even where the return is nil or no deduction is payable.
| How Late the Return Is | Potential Penalty |
|---|---|
| One day late | £100 |
| Two months late | An additional £200 |
| Six months late | £300 or 5% of the deductions due, whichever is higher |
| Twelve months late | A further penalty of at least £300 or 5% of the deductions due, with higher penalties possible where information was deliberately withheld |
HMRC can also impose penalties for inaccurate returns, incorrect employment-status declarations, missing deduction statements and failure to produce records.
Common CIS Mistakes
CIS errors often result from treating the scheme as a simple deduction rather than a complete reporting process.
- Failing to register as a contractor: Businesses may begin paying subcontractors without setting up the required CIS and PAYE processes.
- Not checking employment status: A worker may be treated as self-employed even though the engagement should fall under PAYE.
- Failing to verify subcontractors: This can lead to the wrong deduction rate being used.
- Deducting CIS from VAT: VAT must be removed before the deduction is calculated.
- Deducting CIS from legitimate material costs: This can reduce the subcontractor’s payment incorrectly.
- Accepting unsupported material figures: Contractors should obtain appropriate evidence or make a reasonable assessment.
- Missing monthly returns: Late returns can trigger automatic penalties.
- Failing to submit nil returns: Mainstream contractors must file a nil return or notify HMRC of inactivity from April 2026.
- Not issuing deduction statements: Subcontractors need these statements to support their tax claims.
- Limited companies claiming deductions incorrectly: Deductions suffered should normally be reported through payroll rather than claimed directly on the Corporation Tax return.
How CIS Affects Cash Flow
CIS can have a significant effect on the cash available to subcontractors.
A subcontractor paid under deduction receives less money than the gross value of the work completed. Materials, fuel, insurance, wages and other operating costs may still need to be paid in full.
Good CIS bookkeeping helps a subcontractor understand:
- Total gross income earned.
- Total deductions suffered.
- Net cash received.
- Outstanding customer payments.
- Expected VAT, payroll and tax liabilities.
- Whether a repayment may be due.
Subcontractors should not treat a potential CIS repayment as guaranteed working capital. The final position depends on taxable profit, other liabilities and the accuracy of the records submitted.
Why Professional CIS Bookkeeping Matters
CIS combines subcontractor verification, payment calculations, monthly reporting, payroll, VAT and tax records. A mistake in one part of the process can affect several other filings.
Professional bookkeeping support can help contractors and subcontractors:
- Register for CIS correctly.
- Verify subcontractors before payment.
- Separate labour, materials and VAT accurately.
- Calculate deductions using the correct rate.
- Prepare and submit monthly returns.
- Maintain deduction statements and supporting records.
- Reconcile deductions suffered by subcontractors.
- Coordinate CIS with VAT and payroll reporting.
- Prepare accurate year-end information.
This reduces administrative pressure and gives the business a clearer view of its cash flow and tax position.
Frequently Asked Questions About CIS
What Does CIS Stand For?
CIS stands for the Construction Industry Scheme. It governs how contractors report payments to subcontractors and deduct advance tax from qualifying construction payments.
Who Must Register for CIS?
A business that pays subcontractors for construction work must normally register as a contractor. A non-construction business may also need to register if it meets the £3 million construction expenditure test.
Subcontractors should register if they want to avoid the 30% higher deduction rate.
Is CIS an Additional Tax?
No. CIS deductions are advance payments towards the subcontractor’s eventual tax liabilities. The final position is calculated through Self Assessment or the relevant company reporting process.
How Much Is Deducted Under CIS?
The standard rate is 20% for a registered subcontractor. The higher rate is 30% where the subcontractor is not registered or cannot be verified. No deduction is made where HMRC confirms gross payment status.
Does CIS Apply to Materials?
CIS deductions are not normally applied to qualifying materials purchased directly by the subcontractor. The contractor should obtain evidence or make a reasonable assessment of those costs before calculating the deduction.
Is VAT Included in the CIS Deduction?
No. VAT is excluded before the CIS deduction percentage is applied.
Do I Still Need to File a Tax Return?
Yes. CIS deductions do not replace Self Assessment, Corporation Tax or payroll reporting. The deductions must be recorded through the correct process so they can be offset against the final liability.
Can I Claim a CIS Tax Refund?
A repayment may be due where the deductions suffered exceed the final liabilities. Sole traders normally establish this through Self Assessment. Limited companies claim deductions through payroll and may request repayment of any remaining balance after the tax year.
Can a Business Be Both a Contractor and a Subcontractor?
Yes. A business may receive payments under CIS while also making payments to its own subcontractors. It must maintain records for both sides of the scheme.
Do I Need to File a Nil CIS Return?
From 6 April 2026, mainstream contractors that make no subcontractor payments during a tax month must file a nil return or notify HMRC of a period of inactivity.
How Long Must CIS Records Be Retained?
Contractors must retain CIS records for at least three years after the end of the tax year to which they relate.
Get Help With CIS Bookkeeping
The Construction Industry Scheme is manageable when registrations, verifications, deductions and monthly returns are handled consistently. Problems arise when records are incomplete, deduction calculations are incorrect or reporting is left until the deadline.
Carter Bookkeeping Services Limited supports contractors and subcontractors across the UK with accurate CIS bookkeeping. We can assist with registrations, subcontractor verifications, deduction records, monthly returns, payroll reporting, VAT and year-end reconciliation.
Contact Carter Bookkeeping Services Limited to discuss your current CIS process and the support your construction business requires.